This piece by IMANI’s Associate for Technology Policy and Innovation, John Sitsofe Mensah, addresses the previous capture of the insurance industry by the former finance minister, Ken Ofori-Atta.
Ten to fifteen years ago, SIC Insurance PLC was the undisputed heavyweight of the Ghanaian non-life insurance market, comfortably commanding upwards of 20 to 25 percent of the sector. Around 2014, its grip began to slip significantly, dropping to roughly 16 percent. By 2018, it had lost its apex position entirely.
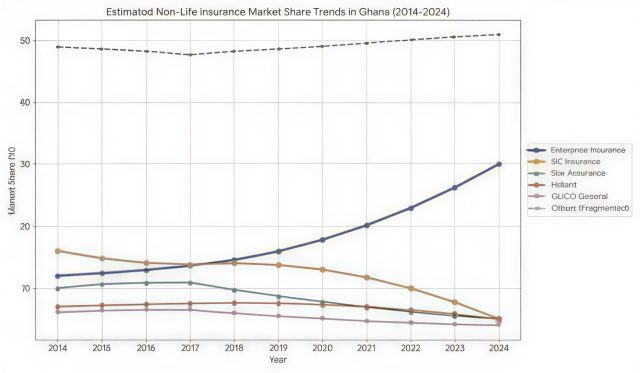
Today, it sits exactly where Franklin Cudjoe described: squeezed into the 4 to 6 percent mid-tier bracket.
However, looking at SIC’s decline in isolation ignores the engineered realities of the broader market. The meteoric ascent of Enterprise Insurance, which now dominates roughly 30 percent of the non-life segment, was not exclusively a triumph of organic, free-market innovation.
While there is no public record of a formal, written state directive mandating that government business be funneled to Enterprise, its aggressive consolidation occurred concurrently with the tenure of a Finance Minister with deep historical and familial ties to the company. Through systemic political alignments and controversial, state-linked consortium deals, such as the insurance of the National Cathedral site and the COVID-19 frontline health workers’ package, state business was perceived to be heavily, if informally, skewed in their direction.
This historical context strips the current State Interests and Governance Authority (SIGA) directive of its noble veneer. What we are witnessing today with the formal, written mandate from SIGA (Reference: SIGA/SOE.SIC/1225) directing State-Owned Enterprises to prioritize SIC is not a novel strategy to “protect state assets.” It is simply the formalization of a deeply flawed, market-distorting playbook.
Whether market distortion is achieved through high-level political patronage (as seen in the recent past) or through explicit bureaucratic fiat (as we are seeing now), the economic outcome is identical. If civil society and industry players rightfully condemned the artificial inflation of a private entity through state capture, then it is intellectually dishonest to justify using the exact same underlying mechanism to provide life support for a struggling SIC now. A bad policy does not miraculously become prudent simply because the political beneficiary has changed, or because the method has shifted from an unwritten nod to a written letter.
Ultimately, the argument against this directive transcends the fortunes of any single company; it is about the survival of the broader Ghanaian macroeconomic ecosystem. The insurance market is not a zero-sum political chessboard. The private businesses operating in this space—entities like Star Assurance, Hollard, GLICO, and dozens of smaller, fragmented players—are critical pillars of our financial services. They pay corporate taxes, remit regulatory levies to the National Insurance Commission (NIC), and employ thousands of Ghanaians.
Those jobs, those tax revenues, and those corporate contributions to the national purse deserve the exact same protection that the state is currently trying to aggressively afford SIC and its shareholders. When the government dictates market share by decree, it crowds out private enterprise, penalizes efficiency, and suffocates its own tax base.
We cannot build a robust, competitive financial sector while the referee continually wears the jersey of a preferred player. All businesses within the space, publicly linked or entirely private, deserve a fair, unmanipulated chance to thrive on the merit of their products and the efficiency of their claims settlements.
When the state picks winners and losers, it is the Ghanaian economy that ultimately pays the premium.